Website / RESOURCE PROFILE

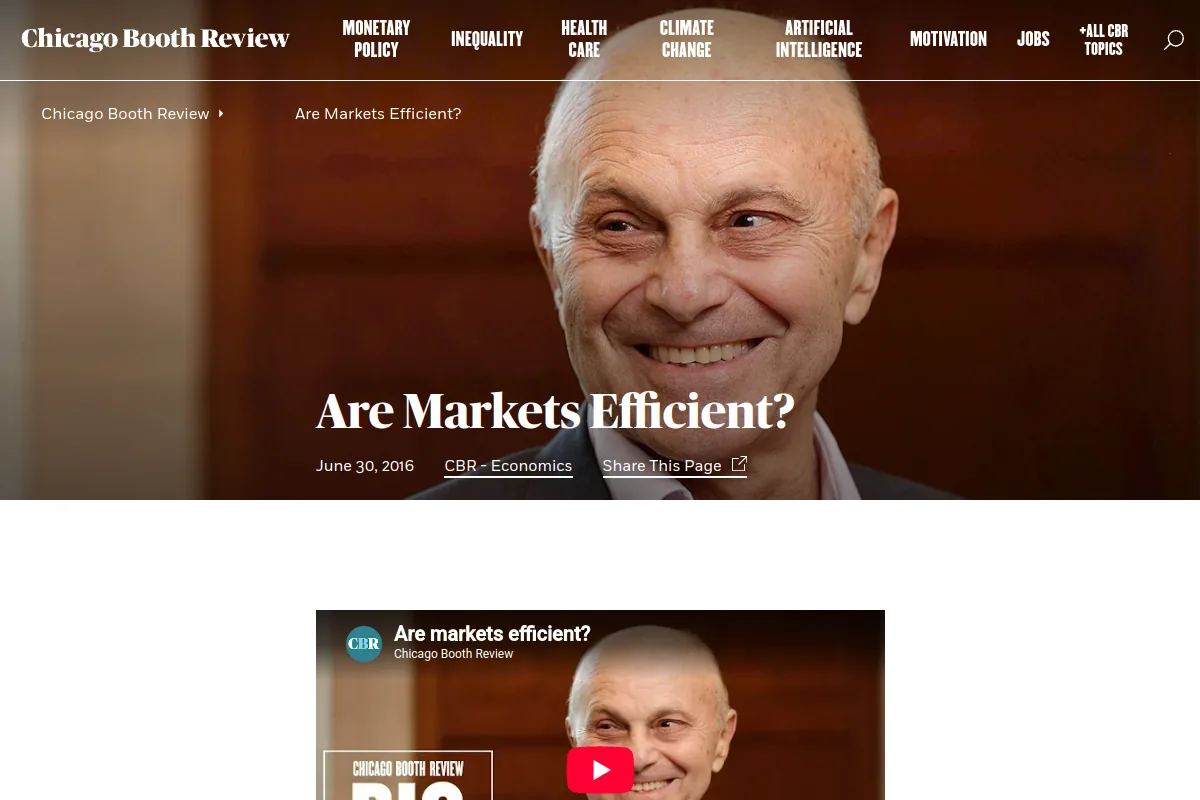
Are Markets Efficient?

Eugene F. Fama and Richard H. Thaler discuss whether markets are prone to bubbles.

review.chicagobooth.edu
Visit source website ↗
Screenshot unavailableResource information and source links remain available. Are Markets Efficient? — reviewed source website screenshot
Reviewed source screenshot · recorded Oct 11, 2026 View source ↗

Overview

Eugene F. Fama and Richard H. Thaler discuss whether markets are prone to bubbles.

Topics & capabilities

algorithmic-tradingresearch-papersfinance

Publisher page information

Source page title
Are Markets Efficient? | Chicago Booth Review
Site name (reported)
The University of Chicago Booth School of Business
Declared page language
en
Observed source URL
https://www.chicagobooth.edu/review/are-markets-efficient ↗
Publisher canonical URL
https://www.chicagobooth.edu/review/are-markets-efficient ↗
Source metadata observed
Oct 11, 2026

Recorded from the source page’s published HTML metadata. Publisher page language can differ from this directory’s English interface.

Source links & provenance

http://review.chicagobooth.edu/economics/2016/video/are-markets-efficient ↗

Discovery references

References explain how this resource entered the collection. They do not represent an endorsement.

Explore related resources

Screenshot unavailableResource information and source links remain available. DeepIntoStreams/TSFM_Finance — reviewed source website screenshot
RepositoryChecked capture

DeepIntoStreams/TSFM_Finance

github.com

the official implementation of the paper “Re(visiting) Time Series Foundation Models in Finance”.

GitHub stars
31
Language
Jupyter Notebook
Code license
Apache-2.0
foundation-modeltime-seriesresearch-lab
96 Authority 96 / 100 Cited by 2 resources in this directory 2 discovery sources Directory record updated: 2026-10-11 How scoring works →

Sign In

Register

Reset Password

Please enter your username or email address, you will receive a link to create a new password via email.