DUCKQUANT / THE QUANT & AI DIRECTORY

Portfolio & Risk

139 resources, ranked by in-directory PageRank

Screenshot unavailableResource information and source links remain available. Bringing clarity to investment decisions | MSCI — reviewed source website screenshot
WebsiteChecked capture

Bringing clarity to investment decisions | MSCI

msci.com

We offer data, analytics and technology designed to help you meet private asset, wealth management, sustainability, index and risk management goals.

Page language
en
Directory citations
1
Discovery sources
1
riskwealthtech
98 Authority 98 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
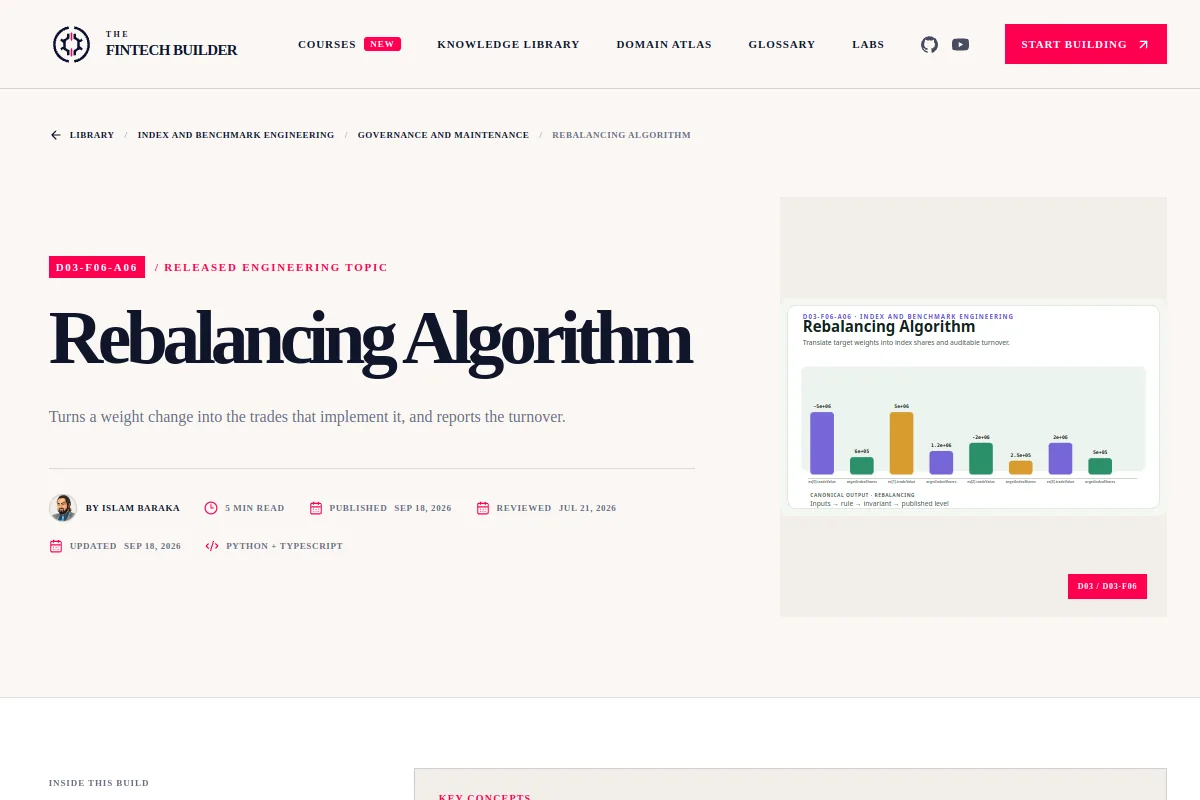
Screenshot unavailableResource information and source links remain available. Portfolio Rebalancer — reviewed source website screenshot
WebsiteChecked capture

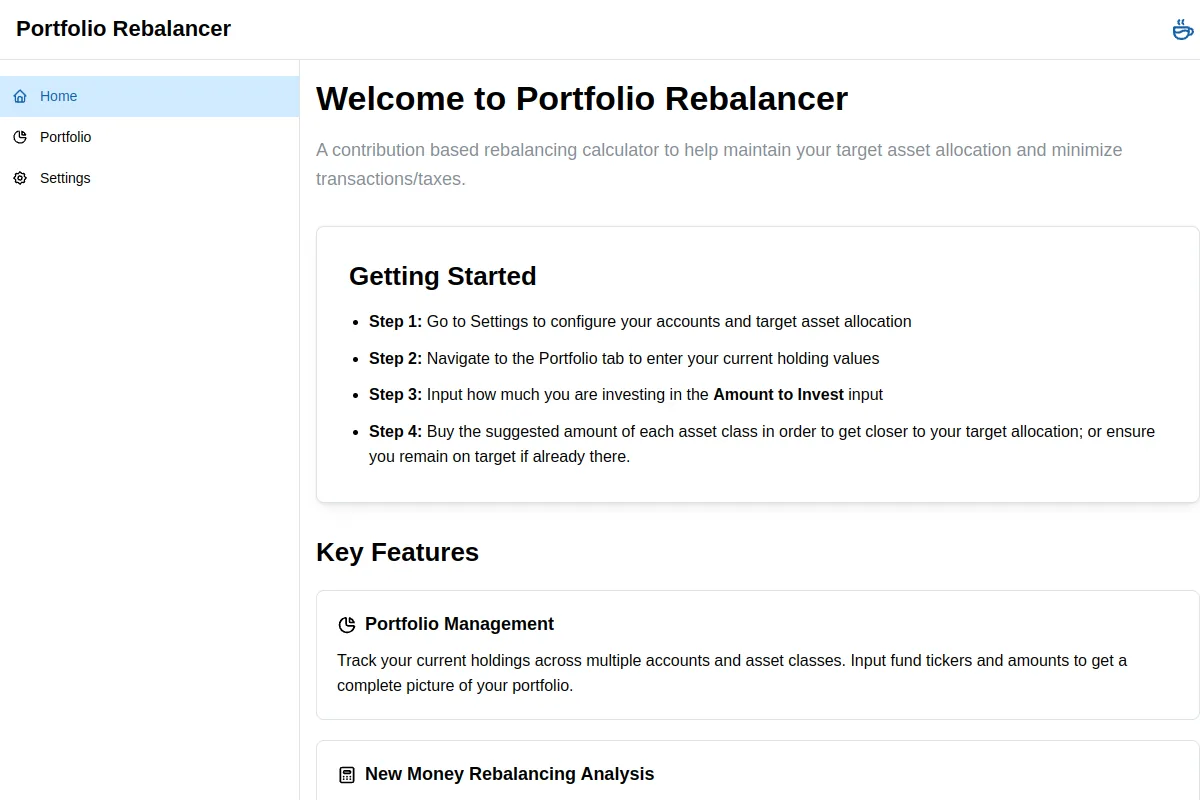
Portfolio Rebalancer

rebalancer.finance

A contribution based rebalancing calculator to help maintain your target asset allocation and minimize transactions/taxes. All data stays private in your browser.

Page language
en
Directory citations
1
Discovery sources
1
portfolio-optimizationfinance
94 Authority 94 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
Screenshot unavailableResource information and source links remain available. Vise — reviewed source website screenshot
WebsiteChecked capture

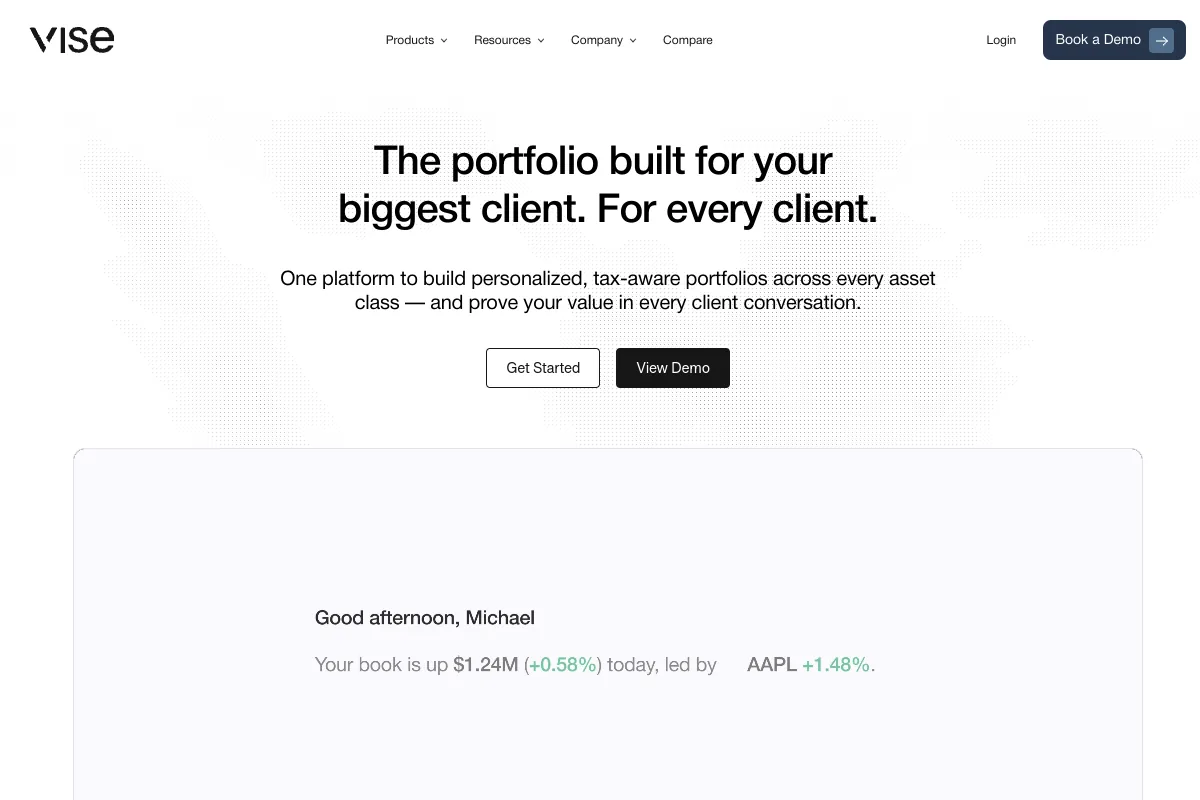
Vise

vise.com

Vise is an AI-driven portfolio management platform that builds and rebalances personalized portfolios for financial advisors

Page language
en
Directory citations
1
Discovery sources
1
productinstitutionalportfolio-construction
94 Authority 94 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
Screenshot unavailableResource information and source links remain available. Portfolio Optimization in Python – skfolio — reviewed source website screenshot
WebsiteChecked capture

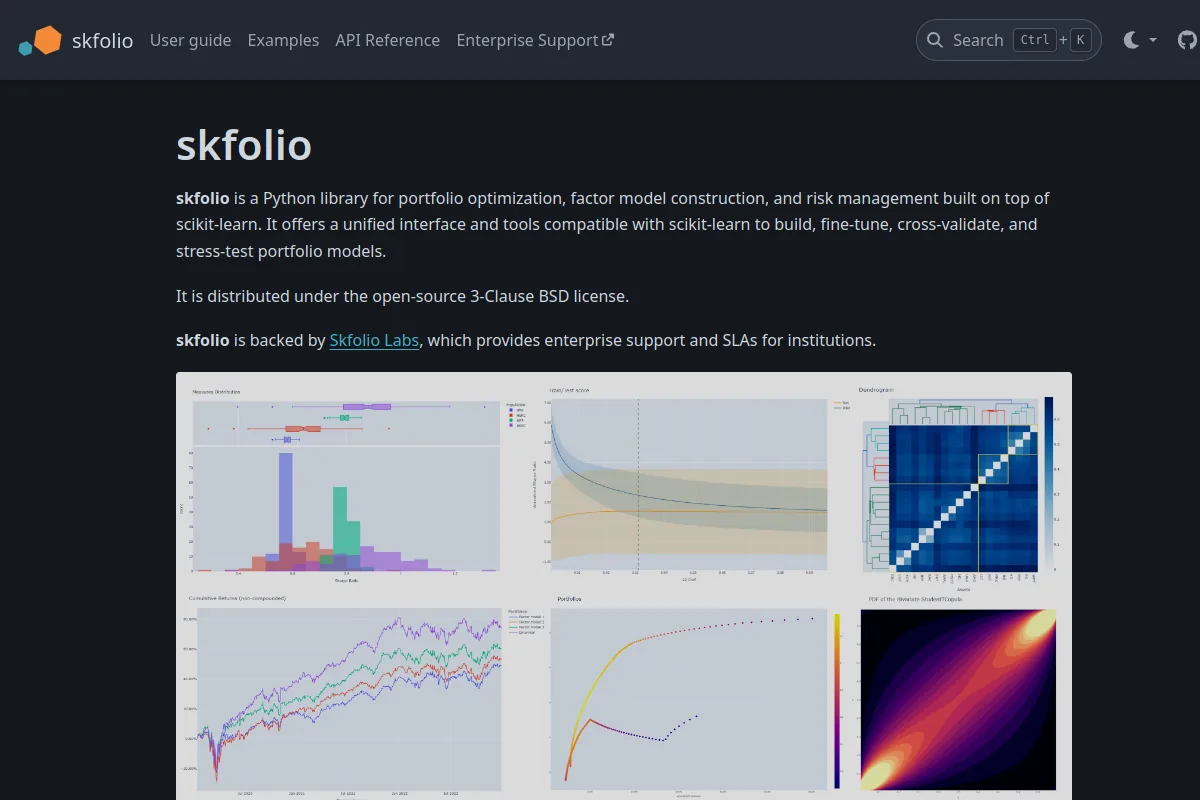
Portfolio Optimization in Python – skfolio

skfolio.org

Python library for portfolio optimization, factor model construction, and risk management, built on scikit-learn to create, fine-tune, cross-validate, and stress-test portfolio models.

Page language
en
Directory citations
1
Discovery sources
1
portfolio-optimizationrisk-management
93 Authority 93 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
Screenshot unavailableResource information and source links remain available. Financial Engineering and Risk Management — Columbia / Coursera — reviewed source website screenshot
WebsiteChecked capture

Financial Engineering and Risk Management — Columbia / Coursera

coursera.org

Offered by Columbia University. Advance Your Knowledge in Financial Engineering . Build the fundamentals and technical skills in financial ... Enroll for free.

Page language
en
Directory citations
1
Discovery sources
1
87 Authority 87 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
Screenshot unavailableResource information and source links remain available. Performance Measurement: The What, Why, and How of the Investment Mana — reviewed source website screenshot
WebsiteChecked capture

Performance Measurement: The What, Why, and How of the Investment Mana

blogs.cfainstitute.org

According to Carl Bacon, CIPM, chairman of StatPro, active investment managers must understand the “what, why, and how” of their past performance in order…

Directory citations
1
Discovery sources
1
algorithmic-tradingarticlesfinance
86 Authority 86 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
Screenshot unavailableResource information and source links remain available. Advanced Risk and Portfolio Management — reviewed source website screenshot
WebsiteChecked capture

Advanced Risk and Portfolio Management

arpm.co

A complete Ecosystem to Master Modern Quantitative Finance. ARPM is an education firm founded by Attilio Meucci.

Page language
en
Directory citations
1
Discovery sources
1
algorithmic-tradingcommunitiesfinance
86 Authority 86 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
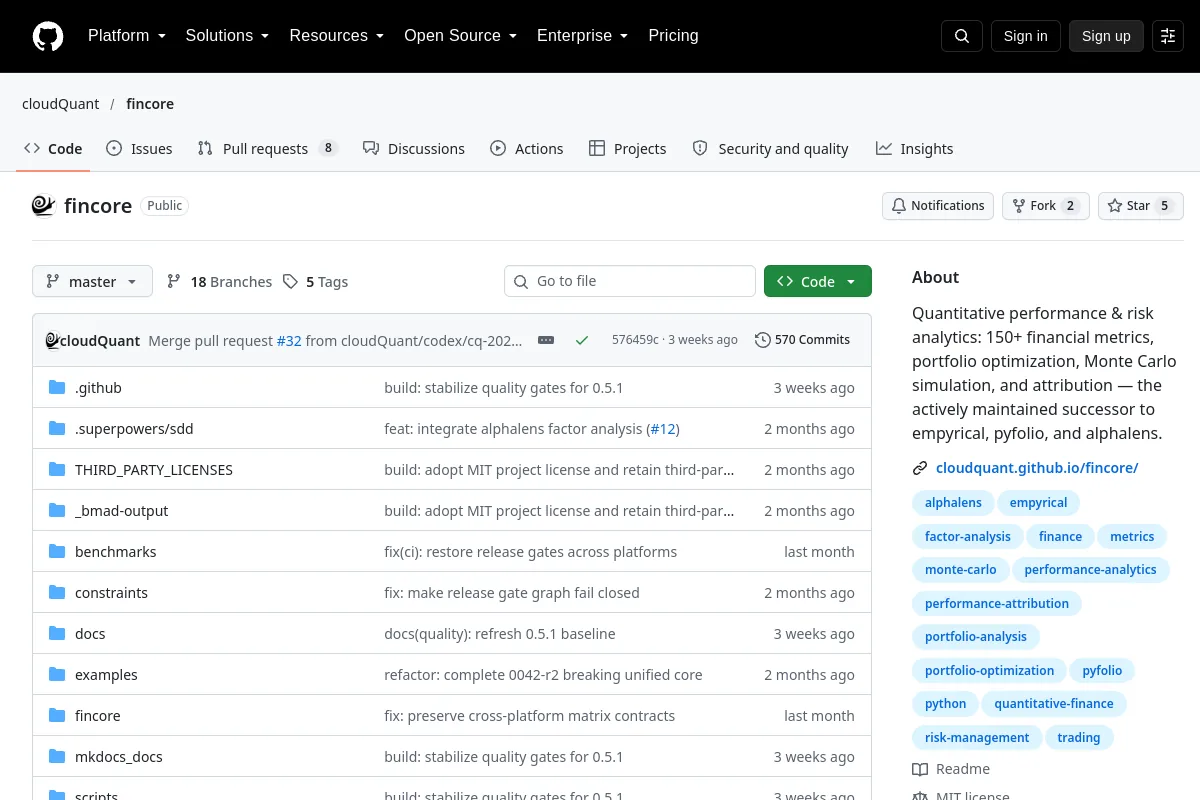
Screenshot unavailableResource information and source links remain available. fincore — reviewed source website screenshot
RepositoryChecked capture

fincore

github.com

Quantitative performance and risk analytics with 150+ metrics, portfolio optimization, Monte Carlo simulation, and attribution; actively maintained successor…

GitHub stars
5
Language
Python
Code license
MIT
quantportfolio-optimizationgithub
72 Authority 72 / 100 Cited by 2 resources in this directory 2 discovery sources Directory record updated: 2026-10-11 How scoring works →
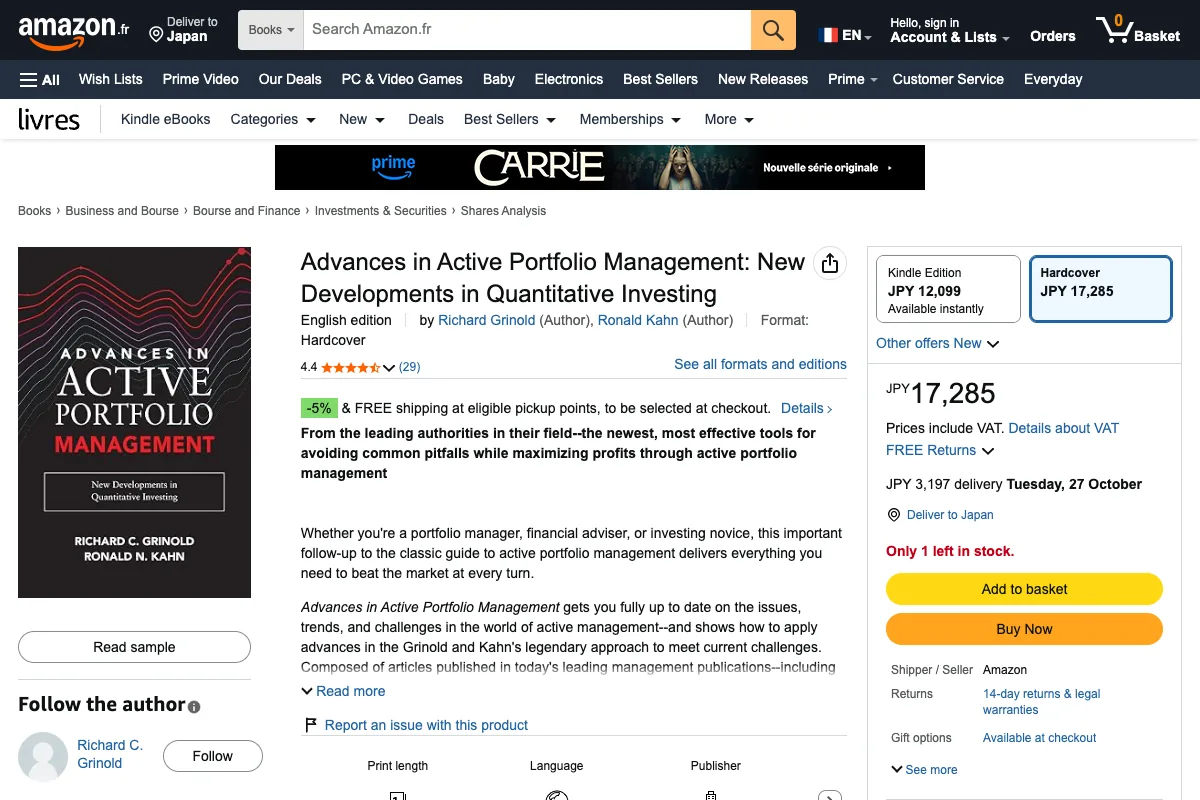
Screenshot unavailableResource information and source links remain available. Advances in Active Portfolio Management: New Developments in Quantitat — reviewed source website screenshot
WebsiteChecked capture

Advances in Active Portfolio Management: New Developments in Quantitat

amzn.to

Advances in Active Portfolio Management: New Developments in Quantitative Investing : Grinold, Richard, Kahn, Ronald: Amazon.fr: Livres

Page language
fr-fr
Directory citations
1
Discovery sources
1
67 Authority 67 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
Screenshot unavailableResource information and source links remain available.
Website

Active Portfolio Management: A Quantitative Approach for Producing Sup

amzn.to

Noté /5. Retrouvez Active Portfolio Management: A Quantitative Approach for Producing Superior Returns and Controlling Risk et des millions de livres en stock sur…

Page language
fr-fr
Directory citations
1
Discovery sources
1
67 Authority 67 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
Screenshot unavailableResource information and source links remain available.
Website

Quantitative Portfolio Management: The Art and Science of Statistical

amazon.co.uk

Buy Quantitative Portfolio Management: The Art and Science of Statistical Arbitrage 1 by Isichenko, Michael (ISBN: 9781119821328) from Amazon's Book Store. Everyday low prices…

Page language
en-gb
Directory citations
1
Discovery sources
1
63 Authority 63 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
Screenshot unavailableResource information and source links remain available. Domains — reviewed source website screenshot
WebsiteChecked capture

Domains

thefintechbuilder.com

Explain where returns and risk came from. Representative subjects: Time- and money-weighted return, Brinson attribution, factor attribution, contribution to return, tracking error, information ratio.

Page language
en
Directory citations
1
Discovery sources
1
63 Authority 63 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
Screenshot unavailableResource information and source links remain available.
Website

Quantitative Portfolio Management: The Art and Science of Statistical

amazon.co.uk

Quantitative Portfolio Management: The Art and Science of Statistical Arbitrage (2021)

Page language
en-gb
Directory citations
1
Discovery sources
1
portfoliolearning
63 Authority 63 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
Screenshot unavailableResource information and source links remain available. Domains — reviewed source website screenshot
WebsiteChecked capture

Domains

thefintechbuilder.com

Estimate borrower and issuer loss. Representative subjects: Credit scoring, PD/LGD/EAD, transition matrices, structural default models, reduced-form hazard models, survival analysis.

Page language
en
Directory citations
1
Discovery sources
1
62 Authority 62 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
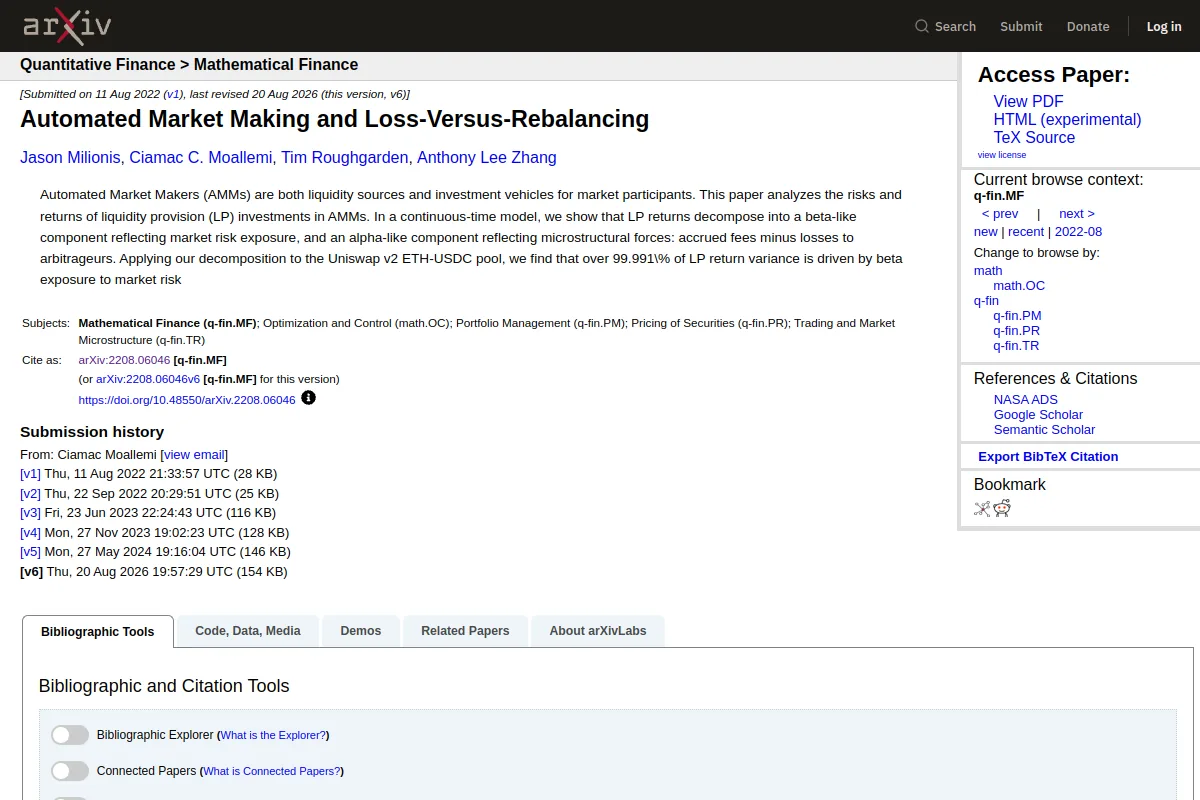
Screenshot unavailableResource information and source links remain available.
Research paper

Modeling Loss-Versus-Rebalancing in Automated Market Makers via Contin

arxiv.org

Publication: Modeling Loss-Versus-Rebalancing in Automated Market Makers via Continuous-Installment Options. Published Aug 5, 2025.

Published
Aug 5, 2025
Authors
8
53 Authority 53 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
Screenshot unavailableResource information and source links remain available. Loss-Versus-Rebalancing under Deterministic and Generalized block-time — reviewed source website screenshot
Research paperChecked capture

Loss-Versus-Rebalancing under Deterministic and Generalized block-time

arxiv.org

Publication: Loss-Versus-Rebalancing under Deterministic and Generalized block-times. Published May 8, 2025.

Published
May 8, 2025
Authors
2
53 Authority 53 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
Screenshot unavailableResource information and source links remain available.
Research paper

Avoiding zero probability events when computing Value at Risk contribu

arxiv.org

Publication: Avoiding zero probability events when computing Value at Risk contributions. Published Apr 28, 2020.

Published
Apr 28, 2020
Authors
3
52 Authority 52 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
Screenshot unavailableResource information and source links remain available. On a multivariate extension for Copula-based Conditional Value at Risk — reviewed source website screenshot
Research paperChecked capture

On a multivariate extension for Copula-based Conditional Value at Risk

arxiv.org

Publication: On a multivariate extension for Copula-based Conditional Value at Risk. Published Aug 22, 2025.

Published
Aug 22, 2025
Authors
1
52 Authority 52 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
Screenshot unavailableResource information and source links remain available. Optimal control of the decumulation of a retirement portfolio with var — reviewed source website screenshot
Research paperChecked capture

Optimal control of the decumulation of a retirement portfolio with var

arxiv.org

Publication: Optimal control of the decumulation of a retirement portfolio with variable spending and dynamic asset allocation. Published Jan 7, 2021.

Published
Jan 7, 2021
Authors
3
52 Authority 52 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
Screenshot unavailableResource information and source links remain available. Robust portfolio selection under Recovery Average Value at Risk — reviewed source website screenshot
Research paperChecked capture

Robust portfolio selection under Recovery Average Value at Risk

arxiv.org

Publication: Robust portfolio selection under Recovery Average Value at Risk. Published Mar 2, 2023.

Published
Mar 2, 2023
Authors
3
52 Authority 52 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
Screenshot unavailableResource information and source links remain available. Constrained Max Drawdown: a Fast and Robust Portfolio Optimization App — reviewed source website screenshot
Research paperChecked capture

Constrained Max Drawdown: a Fast and Robust Portfolio Optimization App

arxiv.org

Publication: Constrained Max Drawdown: a Fast and Robust Portfolio Optimization Approach. Published Jan 5, 2024.

Published
Jan 5, 2024
Authors
1
52 Authority 52 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →
Screenshot review pendingResource information and source links remain available.
Research paper

Discrete-time portfolio optimization under maximum drawdown constraint

arxiv.org

Publication: Discrete-time portfolio optimization under maximum drawdown constraint with partial information and deep learning resolution. Published Oct 29, 2020.

Published
Oct 29, 2020
Authors
3
52 Authority 52 / 100 Cited by 1 resources in this directory 1 discovery sources Directory record updated: 2026-10-11 How scoring works →

Sign In

Register

Reset Password

Please enter your username or email address, you will receive a link to create a new password via email.