AlphaFin
aclanthology.orgAlphaFin benchmarks financial analysis with a retrieval-augmented stock-chain framework and a financial QA dataset
- Published
- May 2024
- Authors
- 7
DUCKQUANT / THE QUANT & AI DIRECTORY
1,058 resources, ranked by in-directory PageRank
AlphaFin benchmarks financial analysis with a retrieval-augmented stock-chain framework and a financial QA dataset
the official implementation of the paper “Re(visiting) Time Series Foundation Models in Finance”.
For the theoretical framework as well as results from the running code see
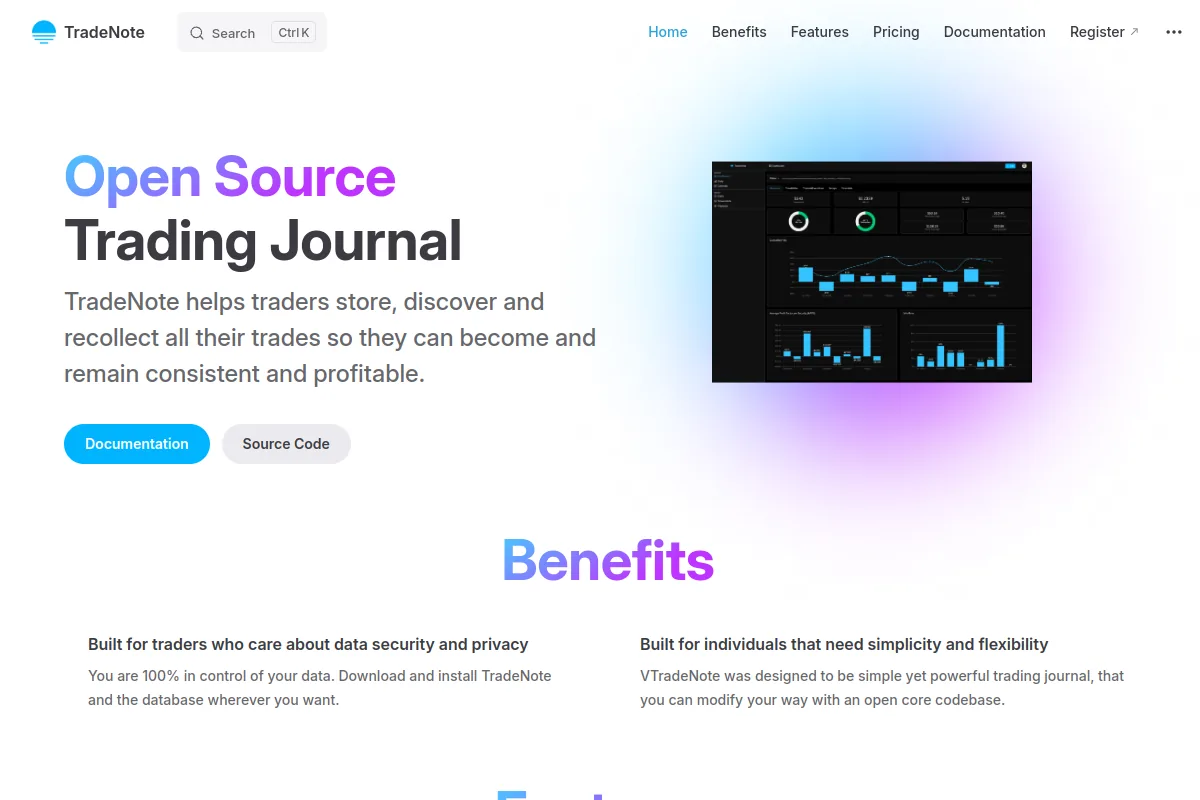
TradeNote is an open source trading journal that helps traders store, discover and recollect all their trades so they can become and remain consistent…
Import or sync trades, review performance, and keep your journal as files on your own device. Journalit runs inside Obsidian, a free note-taking app.
Log every fill, size the trade before you take it, and see what your record actually says. Self-hostable in one command. The journal shows…
This study researches the topic of trading futures spreads, that is, trading the pricing differential between two futures contracts. We trade an equally we
IDEAS is a central index of economics and finance research, including working papers, articles and software code
Publication: ZeroQ: A Novel Zero Shot Quantization Framework. Published Jan 1, 2020.
A Comprehensive Overview of Security and Trust Assumptions in Blockchain Bridges.
. Zhang, Zihao, Stefan Zohren, and Stephen Roberts. The Journal of Financial Data Science 2, no. 2 (2020): 25-40
Explore this resource at its source website for documentation and current information.
This article presents a simple quantitative method that improves risk-adjusted returns across various asset classes. A moving-average timing model is tested in-sample on the…
In this article, the authors conduct a horse race between representative risk parity portfolios and other asset allocation strategies, including equal weighting, minimum variance,…
Publication: ActQuant: Sub-4-bit Action-Guided Quantization for Vision-Language-Action Models. Published May 19, 2026.
Publication: HBVLA: Pushing 1-Bit Post-Training Quantization for Vision-Language-Action Models. Published Feb 14, 2026.
Publication: QuantWAMs: Calibrating at the Right Granularity for World Action Models. Published Jul 30, 2026.
Publication: FAST: Efficient Action Tokenization for Vision-Language-Action Models. Published Jan 16, 2025.
Publication: Quantization-Aware Imitation-Learning for Resource-Efficient Robotic Control. Published Dec 2, 2024.
Publication: QuantVLA: Scale-Calibrated Post-Training Quantization for Vision-Language-Action Models. Published Feb 23, 2026.
Publication: BitRL: Reinforcement Learning with 1-bit Quantized Language Models for Resource-Constrained Edge Deployment. Published Apr 27, 2026.
Publication: VLA-Forget: Vision-Language-Action Unlearning for Embodied Foundation Models. Published Apr 5, 2026.
Publication: Mechanistically Interpreting Compression in Vision-Language Models. Published Mar 26, 2026.
Publication: Less Precise Can Be More Reliable: A Systematic Evaluation of Quantization's Impact on VLMs Beyond Accuracy. Published Sep 25, 2025.
" FinRL-Meta: Market Environments and Benchmarks for Data-Driven Financial Reinforcement Learning ." NeurIPS 2022 .
Explore this resource at its source website for documentation and current information.
Eugene F. Fama and Richard H. Thaler discuss whether markets are prone to bubbles.
AI-native modular infrastructure for quantitative trading. Unifies data, strategy, backtesting, and execution. Paper
Publication: Quantum-Enhanced Forecasting for Deep Reinforcement Learning in Algorithmic Trading. Published Sep 11, 2025.
Publication: MarketSenseAI 2.0: Enhancing Stock Analysis through LLM Agents. Published Feb 1, 2025.
Publication: A Deep Reinforcement Learning Approach to Automated Stock Trading, using xLSTM Networks. Published Mar 12, 2025.
Explore this resource at its source website for documentation and current information.
Dynamic Datasets and Market Environments for Financial Reinforcement Learning
. Jiang, Zhengyao, Dixing Xu, and Jinjun Liang. arXiv preprint arXiv:1706.10059 (2017)
International Conference on AI in Finance, ICAIF 2020