Hugging Face
huggingface.coPlatform for publishing models, datasets, and machine learning applications. This record links to the platform homepage.
- Directory citations
- 1
- Discovery sources
- 3
Repository / RESOURCE PROFILE
Credit Value Adjustment (CVA) calculation for interest rate swaps using a risk neutral Libor Market Model (LMM) calibrated to european swaption implied volatilities.
Source: GitHub API · observed Oct 11, 2026. Stars and forks are recorded counts. Repository code licenses may differ from dataset or model-weight licenses.
References explain how this resource entered the collection. They do not represent an endorsement.
Platform for publishing models, datasets, and machine learning applications. This record links to the platform homepage.
Developer platform for hosting and collaborating on software repositories. This record links to the platform homepage.
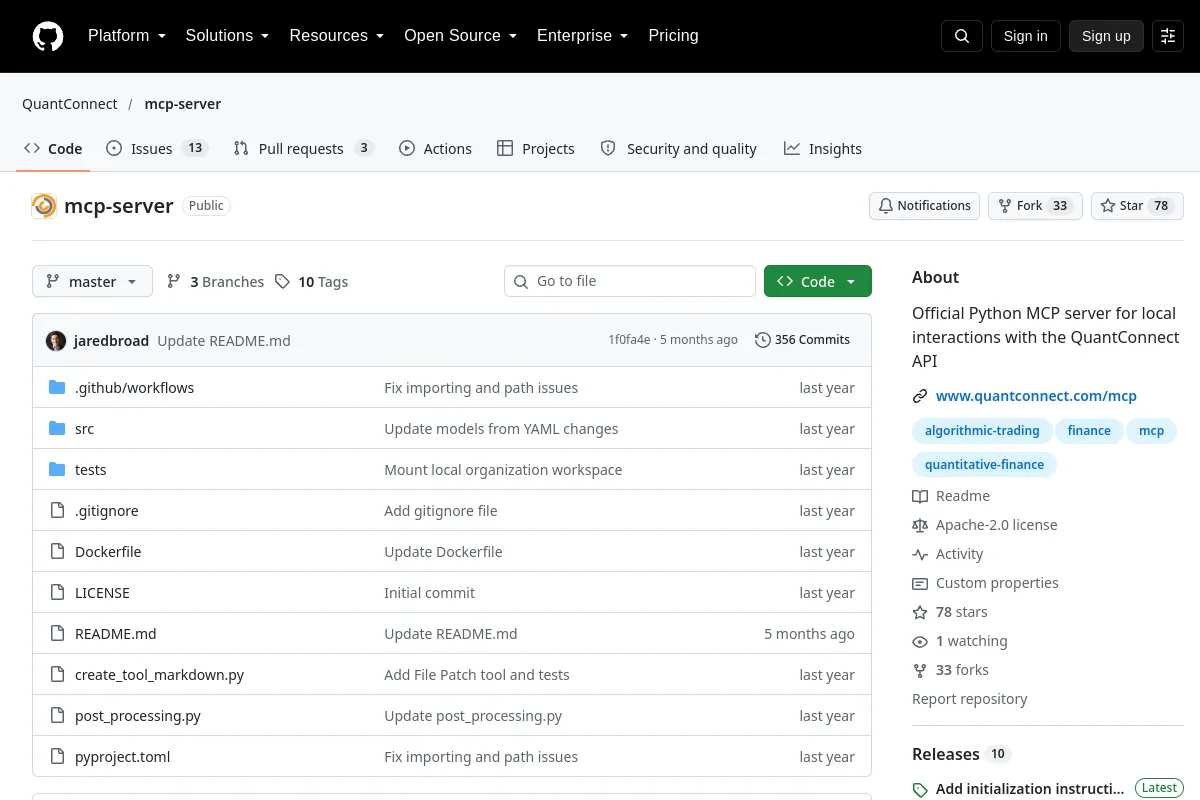
Official QuantConnect MCP server: write Python trading strategies, run cloud backtests, and deploy live algorithms