Repository / RESOURCE PROFILE

heston

Implementations of the Heston stochastic volatility model

github.comR
Visit source website ↗

Overview

Implementations of the Heston stochastic volatility model

Topics & capabilities

financernumerical-codesoption-pricing

Repository information

Repository
daleroberts/heston ↗
Repository owner
daleroberts
Primary language
R
Repository code license
BSD-3-Clause ↗
Maintenance status
Not archived at the recorded check
Forked repository
No
GitHub stars
24
Forks
17
Default branch
master
Last repository push
Apr 15, 2015

Source: GitHub API · observed Oct 11, 2026. Stars and forks are recorded counts. Repository code licenses may differ from dataset or model-weight licenses.

Source links & provenance

https://github.com/daleroberts/heston ↗

References explain how this resource entered the collection. They do not represent an endorsement.

Explore related resources

Screenshot unavailableResource information and source links remain available.
Website

GitHub

github.com

Developer platform for hosting and collaborating on software repositories. This record links to the platform homepage.

Page language
en
Directory citations
3
Discovery sources
3
ai-quant-directorypysystemtradesetup
98 Authority 98 / 100 Cited by 3 resources in this directory 3 discovery sources Directory record updated: 2026-10-14 How scoring works →
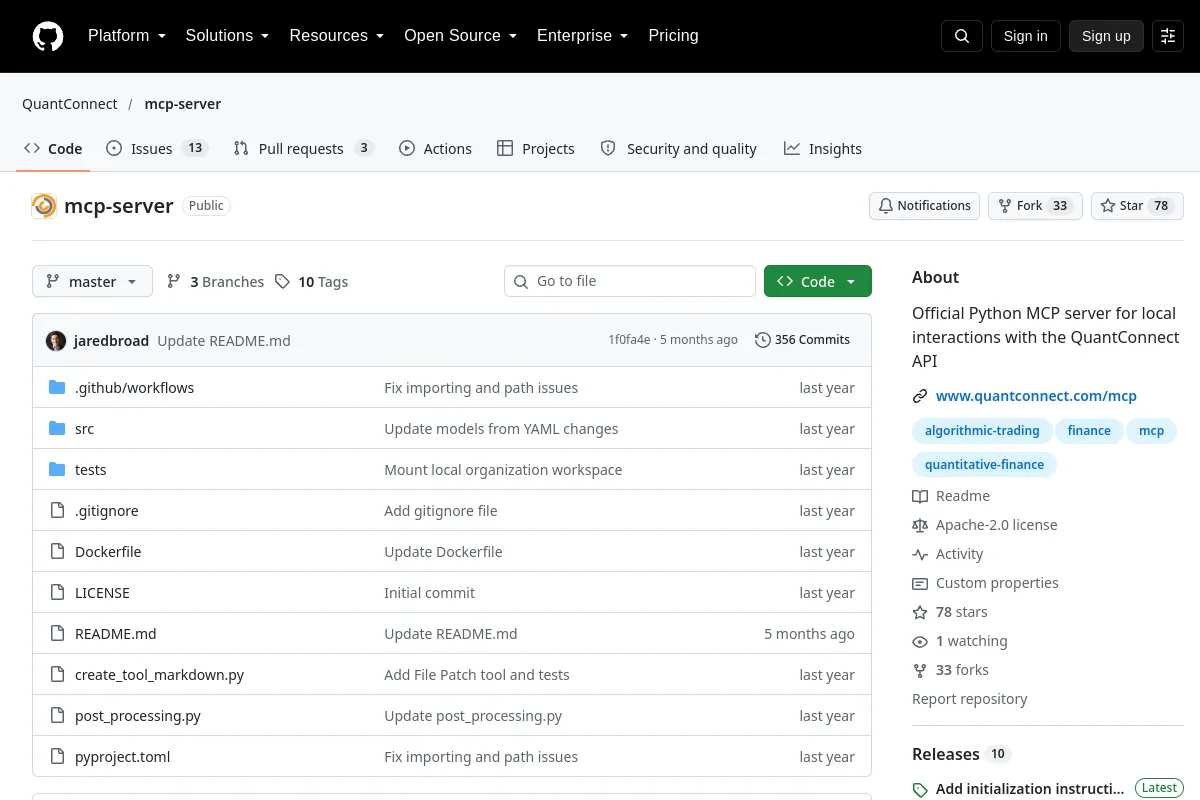
Screenshot unavailableResource information and source links remain available. QuantConnect/mcp-server — reviewed source website screenshot
RepositoryChecked capture

QuantConnect/mcp-server

github.com

Official QuantConnect MCP server: write Python trading strategies, run cloud backtests, and deploy live algorithms

GitHub stars
78
Language
Python
Code license
Apache-2.0
ai-in-financemcp-serversgithub
97 Authority 97 / 100 Cited by 3 resources in this directory 3 discovery sources Directory record updated: 2026-10-11 How scoring works →

Sign In

Register

Reset Password

Please enter your username or email address, you will receive a link to create a new password via email.