TRADES diffusion market simulation
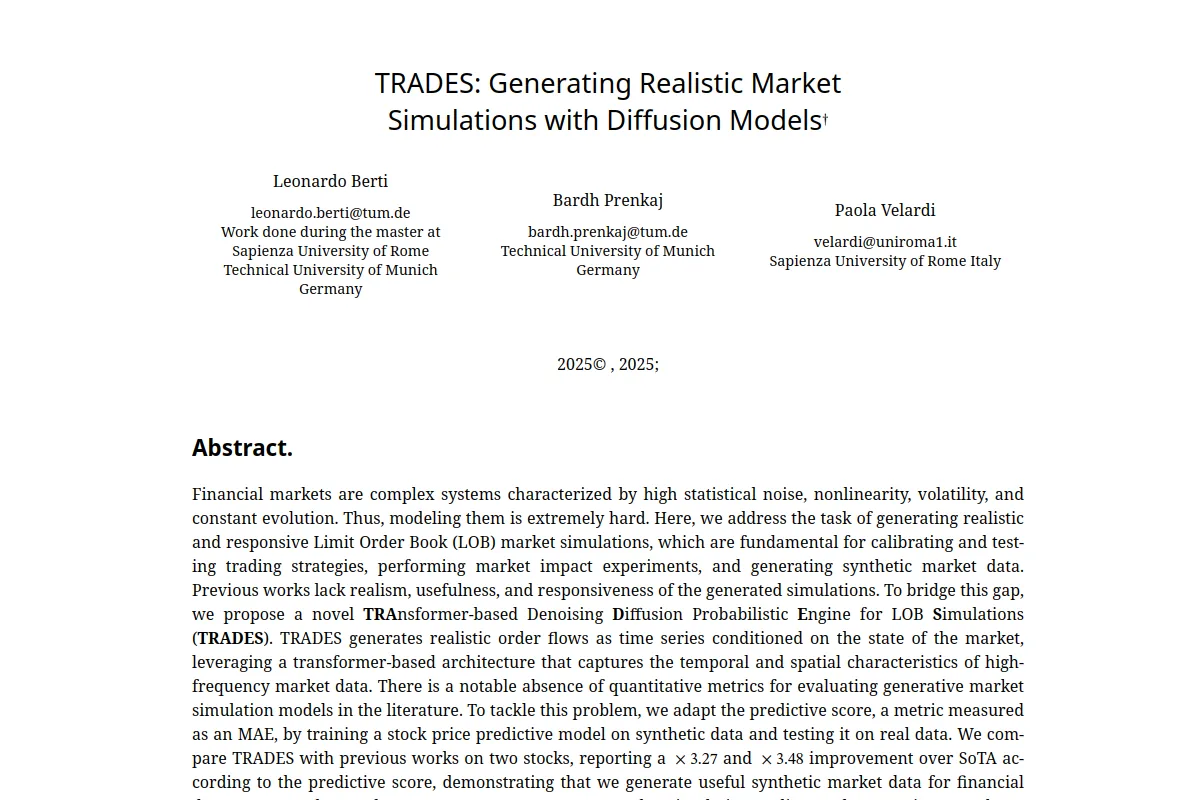
ar5iv.labs.arxiv.orgTRADES is a diffusion-based generator of realistic limit-order-book market simulations for downstream trading research
- Published
- Jan 31, 2025
- Authors
- 3
Repository / RESOURCE PROFILE
This project uses Python to create an optimally weighted stock portfolio by combining 7 common technical indicators, generating trading signals, backtesting the strategy, and aiming to outperform the standard buy-and-hold strategy of the SPY ETF.
Source: GitHub API · observed Oct 11, 2026. Stars and forks are recorded counts. Repository code licenses may differ from dataset or model-weight licenses.
References explain how this resource entered the collection. They do not represent an endorsement.
TRADES is a diffusion-based generator of realistic limit-order-book market simulations for downstream trading research
Research, backtest and live trade multi-asset quantitative strategies on the world's leading open-source algorithmic trading platform, alongside 552,100 quants.
Commercial extension of VectorBT adding advanced analytics, live trading and data integrations.