Deep Learning for Limit Order Books
arxiv.orgEarly work applying deep neural networks to limit-order-book representation and price prediction.
- Published
- Jan 8, 2016
- Authors
- 1
DUCKQUANT / THE QUANT & AI DIRECTORY
14,444 resources, ranked by in-directory PageRank
Showing 2,593–2,628 of 14,444 resources
Early work applying deep neural networks to limit-order-book representation and price prediction.
Deep convolutional architecture predicting price movements directly from limit-order-book data.
Reinforcement-learning approach resolving latency and inventory risk in market-making strategies.
Applies reinforcement learning to high-frequency market-making with inventory and adverse-selection risk.
Presents a modular, reusable framework for reinforcement-learning-based optimal execution.
Studies reinforcement-learning approaches for optimal order execution under market impact.
Develops deep reinforcement-learning policies for online optimal trade-execution problems.
Deep reinforcement-learning framework for dynamic portfolio optimisation tested on China's stock market.
Applies deep reinforcement learning to high-dimensional stock portfolio trading problems.
Uses deep reinforcement learning to learn long-short portfolio allocation policies.
Reports on the FinRL contest series benchmarking data-driven financial reinforcement-learning agents.
FinceptTerminal is a modern finance application offering advanced market analytics, investment research, and economic data tools, designed for interactive.
Chinese financial assistant benchmark assessing LLM ability across financial tasks.
Chinese financial-domain knowledge benchmark for evaluating large language models.
Bridges numerical and textual modalities in a unified time-series foundation model.
Applies a time-series foundation model to realised-volatility forecasting in financial markets.
Evaluates pretrained time-series foundation models on cross-sectional financial return forecasting.
Fine-tunes a pretrained time-series foundation model on financial data for forecasting tasks.
Open probabilistic time-series foundation model based on a lagged decoder-only transformer.
Adds sparse mixture-of-experts routing to time-series foundation models.
Extends the Chronos foundation model to universal multivariate and covariate-aware forecasting.
Trains a universal time-series forecasting transformer across many domains and frequencies.
Tokenises time series and pretrains a language-model-style foundation model for forecasting.
Evaluates feature-engineering choices for deep-learning mid-price prediction on order-book data.
Models information persistence and structure in limit-order-book data with heterogeneous graphs.
Transformer with dual attention for price-trend prediction from limit-order-book data.
Financial LLM framework producing interpretable stock movement predictions with rationales.
Uses LLM prompting to extract explainable return-predictive factors from news text.
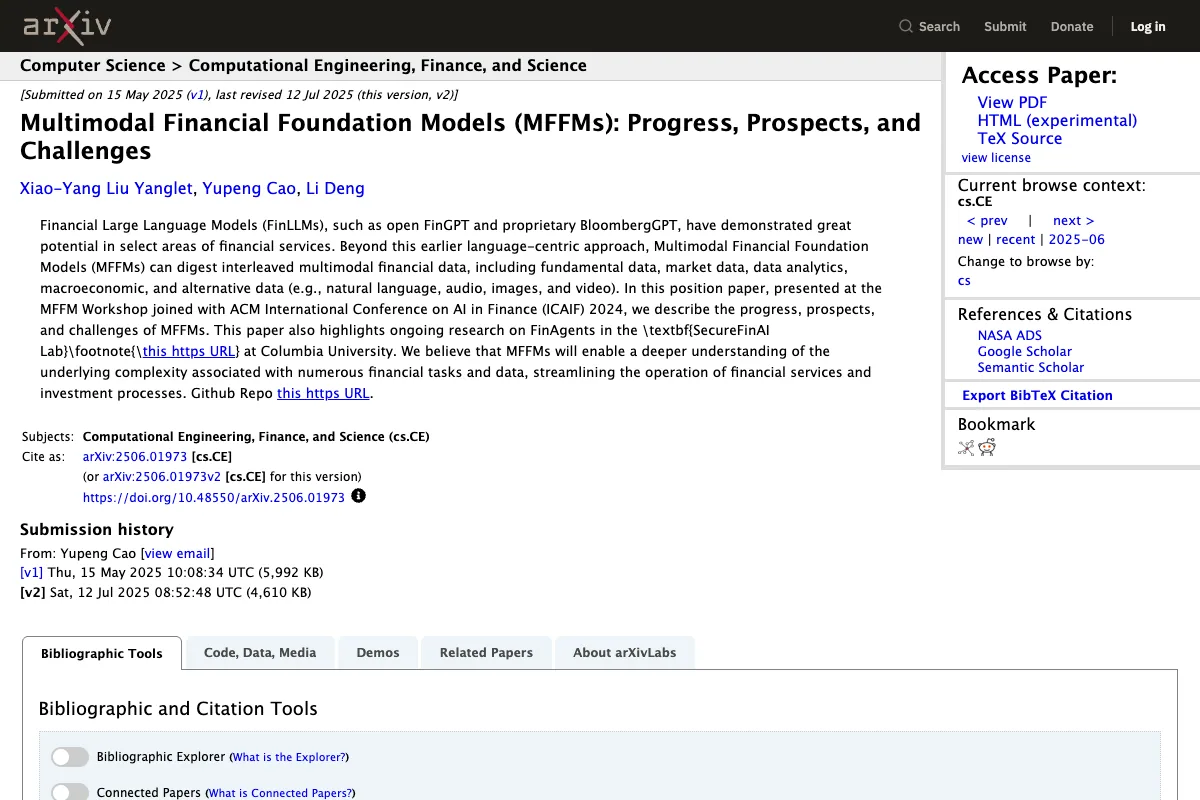
Survey of multimodal financial foundation models combining text, tables, audio and time series.
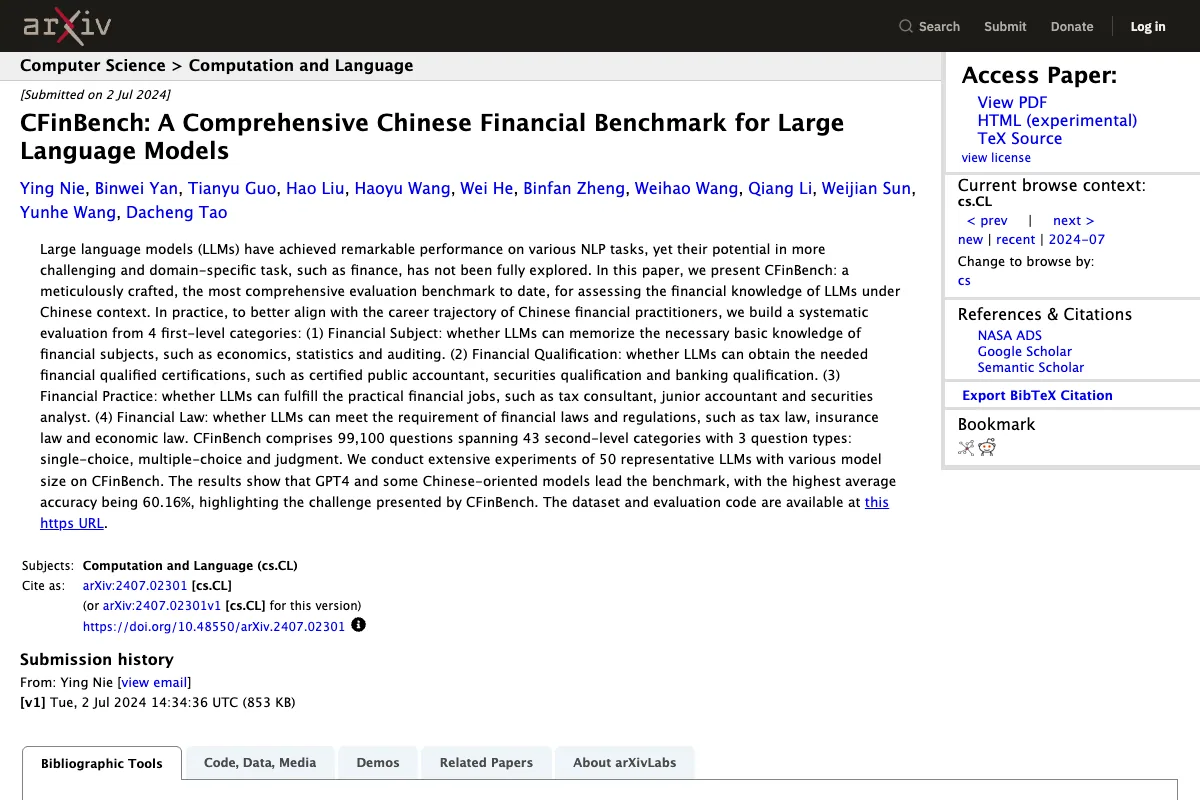
Comprehensive Chinese financial benchmark covering knowledge, reasoning and safety for LLMs.
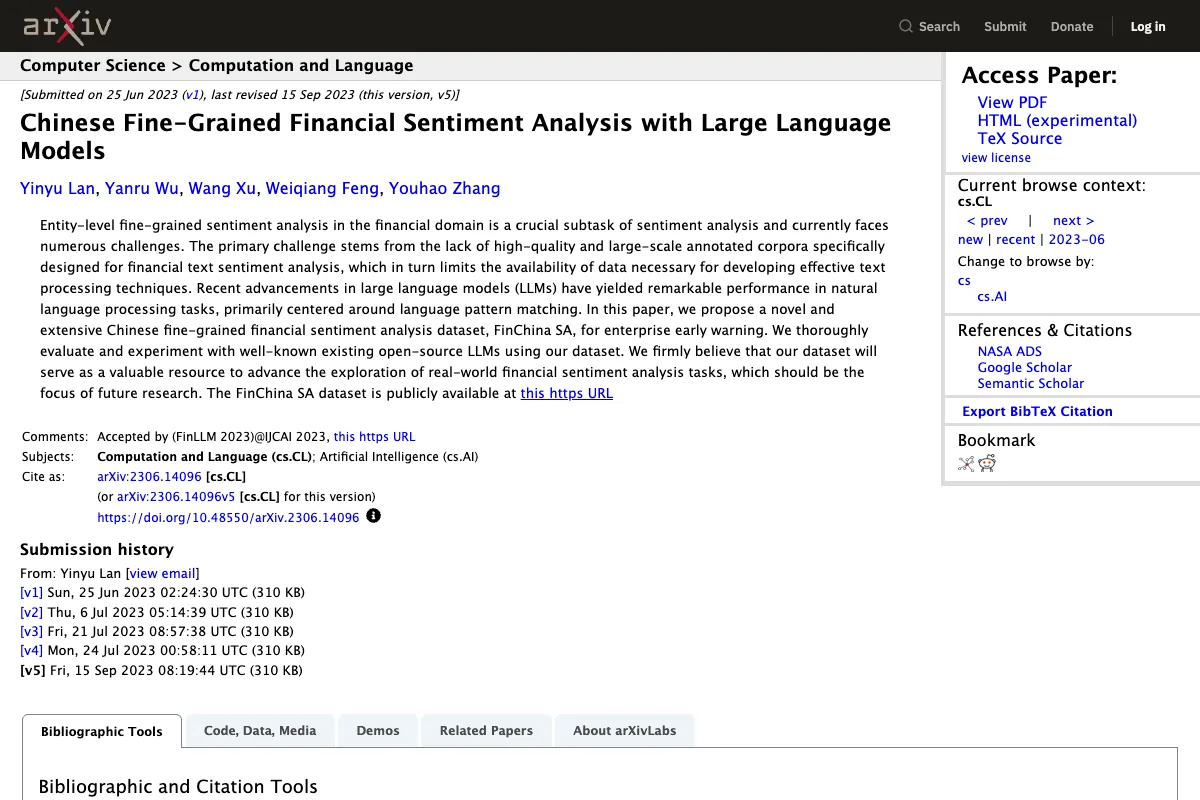
Builds a Chinese fine-grained financial sentiment dataset and evaluates LLMs on it.
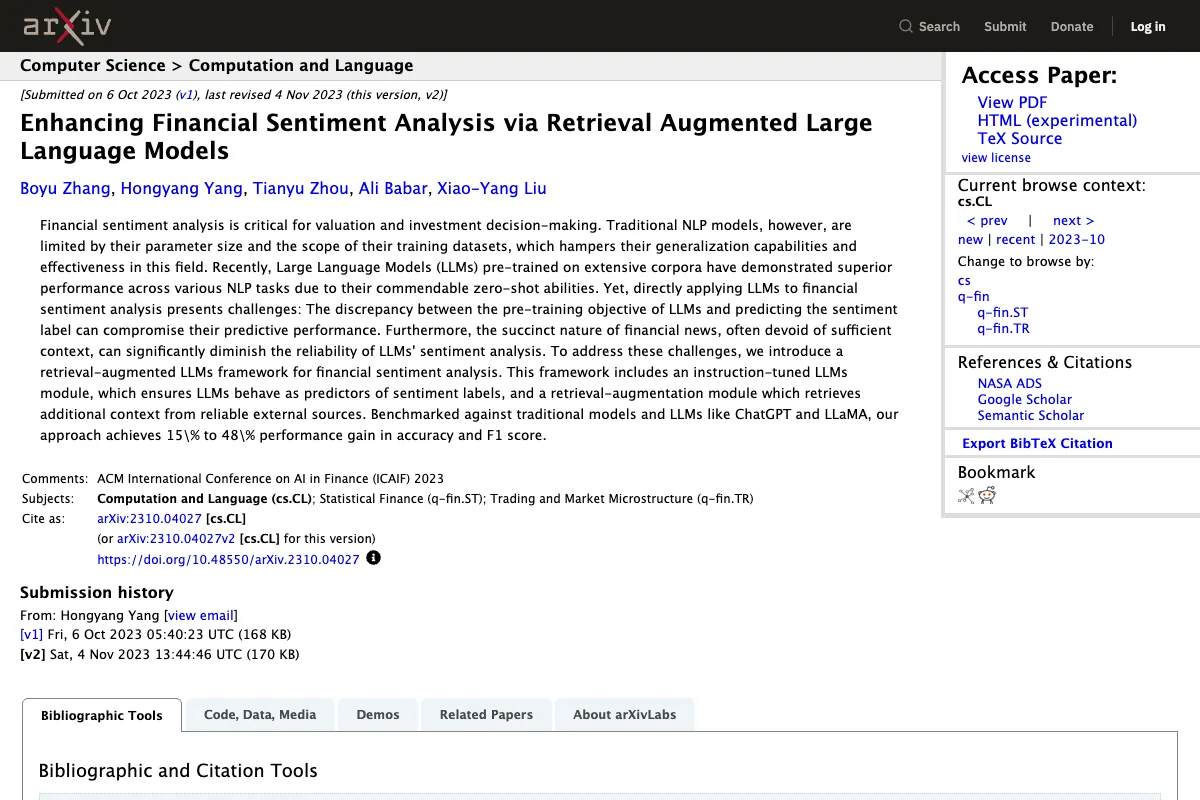
Retrieval-augmented generation improves LLM accuracy on financial sentiment classification.
Uses direct preference optimisation to align LLMs for sentiment-driven algorithmic trading.
Instruction-tunes general-purpose LLMs to perform financial sentiment analysis.
Combines multiple expert LLMs to produce trading decisions from heterogeneous data.
End-to-end tool-augmented agentic reinforcement-learning framework for stock trading.